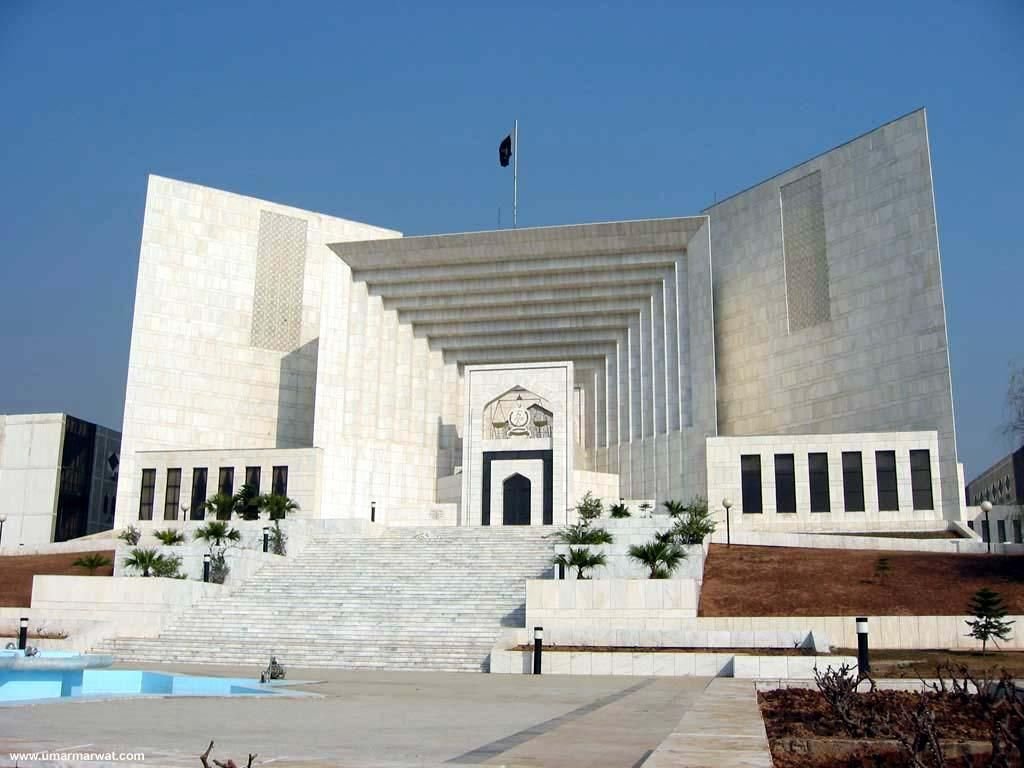
ISLAMABAD, Oct 30 (APP):The Supreme Court has ruled that surplus generated in a pension fund cannot be treated as a bank’s taxable income under the Income Tax Ordinance, 2001, unless the amount is actually refunded to the employer.
In a judgment authored by Justice Aqeel Ahmed Abbasi, the court held that under Rule 4 of Part II of the Sixth Schedule, contributions made by an employer to a pension fund, or income earned thereon, become taxable in the tax year in which the amount is actually received back by the employer.
The court observed that although banks are subject to a special tax regime under the Seventh Schedule, it contains no specific provision governing surplus arising from pension funds. Therefore, the relevant provisions of the Sixth Schedule apply through Rule 9 of the Seventh Schedule.
The judgment clarified that annual actuarial valuations under International Accounting Standard (IAS) 19 may show a surplus or deficit in pension fund assets and liabilities, but merely recording a surplus in financial statements does not make it taxable income.
It further held that accounting principles cannot determine tax liability independently of the applicable tax law, while tax authorities cannot reject a bank’s consistently followed accounting practice without sound legal grounds.
A three-member bench comprising Justice Irfan Saadat Khan, Justice Aqeel Ahmed Abbasi and Justice Shakeel Ahmed dismissed a civil appeal filed by the Commissioner Inland Revenue against MCB Bank, upholding the Lahore High Court’s judgment.
Source: APP (Associated Press of Pakistan)